The Sub-Prime Graphics Crisis

Video thumbnail: The Sub-Prime Graphics Crisis
Nov 10, 202626m 52s video lengthHow Money Works

The Signal

The AI investment boom has pivoted from cash-funded growth to a debt-heavy cycle characterized by record-breaking borrowing and deteriorating core-business financials. While hardware scarcity currently provides a veneer of collateral-backed security for lenders, the industry is increasingly tethered to a circular financing loop. The central tension lies in whether this debt-fueled infrastructure expansion can deflate slowly or is structurally primed for a hard unwind should hardware demand soften.

The Case

The Shift to Debt

  • AI companies borrowed a reported $489 billion in the first half of this year, a shift from cash-rich balance sheets to heavy reliance on junk-rated bonds and high-interest debt.
  • Google, a foundational tech giant, recently posted its first negative free cash flow in 22 years, signaling that the AI buildout is straining even the most profitable core search businesses.1:12
  • Borrowing costs have surged for the sector; unsecured lending is now above 15%, while premiums on credit default swaps—a derivative used to hedge default risk—have spiked, exemplified by Oracle’s debt insurance costs climbing near 300 basis points.2:08

Collateral and Circularity

  • Infrastructure lending is now frequently secured by chips and data centers, turning compute capacity into collateral; for example, CoreWeave—a specialized cloud provider—closed an $8.5 billion loan backed by Nvidia hardware.10:18
  • This structure depends on hardware retaining value, which remains inconsistent; while some older chips have appreciated due to scarcity, rental rates for H100s have fluctuated, and the entire chain relies on competitors renting capacity from one another in deals like OpenAI’s $38 billion commitment to Amazon.5:16

The International Precedent

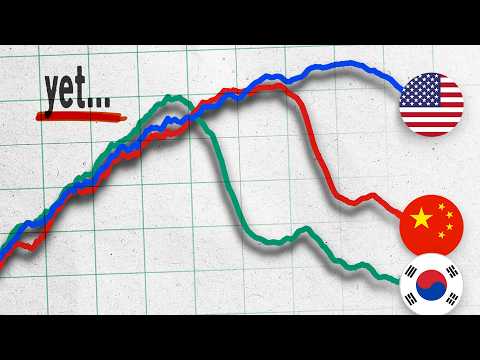
  • China’s Star 50 index and the South Korean market have already corrected by approximately 40% from their peaks, though those economies were more concentrated in hardware components and supply-chain firms than the U.S. market.2:30
  • Whether U.S. tech firms, which focus more on the narrative of 'superintelligence,' can avoid the sharper supply-chain corrections seen abroad remains the key unanswered question in the current financial cycle.24:04

The 1 Minute Signal Take

The current AI lending environment is fundamentally fragile because it relies on high collateral values that are only as stable as end-demand for compute. While the system has not fully collapsed, the accumulation of debt makes a gentle correction increasingly difficult, as even minor slowdowns now magnify systemic interest expenses and credit risk.

Pro Analysis

Why It Matters

This is a transition from an 'innovation phase' to a 'financial engineering phase'. When the biggest tech companies in history start running negative cash flow to fund infrastructure, they move from being the market's stabilizers to its primary source of systemic risk. The shift from equity-funded growth to debt-fueled expansion means the industry is no longer shielded from the broader credit cycle.

Strategic Implications

Companies should pivot toward capital efficiency. The 'grow at all costs' model is becoming prohibitively expensive as credit spreads widen. For investors, the reliance on asset-backed lending means hardware liquidation risk is now a proxy for equity risk.

Evidence & Hype Audit

The content is high-signal regarding financial trends (bond yields, cash flow, loan structures) but contains some rhetorical hyperbole ('cyber slum lord', 'subprime'). The use of Google's cash flow and the $489B debt figure provides hard grounding, though the link between U.S. and Asian market corrections is speculative rather than causal.

Counterarguments

One could argue that AI hardware is unlike subprime housing because it is productive capital. A GPU generates revenue in a way a house does not; if demand is high, the hardware pays for itself. If current scarcity persists, the depreciation schedules might actually be conservative, not aggressive.

Who Should Care

  • Corporate Treasurers: Need to re-evaluate the risk of holding AI-linked debt.
  • Tech Investors: Must distinguish between 'shovel sellers' (hardware/components) and 'miners' (application layers).
  • Infrastructure Operators: Must stress-test their models against a 30-50% drop in rental utilization.

What to Do Next

  • Monitor quarterly disclosures for shifts from cash to debt-financed capex.
  • Track H100/A100 rental rates on major cloud platforms as a proxy for hardware demand.
  • Watch credit spreads for major Neocloud providers; widening spreads are the first sign of liquidity stress.
  • Compare depreciation schedules across your portfolio; look for companies shifting to 6+ year timelines.
  • Audit your exposure to firms heavily reliant on circular revenue from other AI-focused entities.
Time saved:23m 14s

Share this

Tags

Written by: 1 Minute Signal Editorial Team